Essentially since the dawn of modern insurance, at least when it comes to building and contents insurance, one principle has applied: only a risk that is specifically named in the policy is covered. In the past, many clients found out under genuinely dire circumstances what the difference is between a flood and inundation. However, if you take out travel insurance covering medical expenses abroad, you know that the principle is reversed. The insurer is essentially not interested in what you were doing at the moment you were injured, unless it was one of the activities specifically listed in the policy as excluded from cover. These include risky sports, hiking or skiing in high mountain areas and off marked trails.
Propositional logic takes the lead
So-called all-risk building and contents insurance, i.e. covering all risks, has newly started to be offered by some insurers to house and flat owners too. All-risk policies contain no list of named perils, quite the opposite – they apply the open perils principle. Anything not specifically listed as uninsurable is therefore automatically covered. This simplifies the administration of the whole process and at the same time minimises the risk of disputes between the insured and the insurer.
A civil dispute with an insurance company can cost you hundreds of thousands of crowns in expenses
It is the same principle familiar to IT staff who work in information and communication network security. They have two options: either allow network traffic only from selected devices placed on a “whitelist” (the term “allowlist” is also used at times). Or allow it for everyone except devices on a “blacklist” (or, in more modern parlance, a “blocklist”). The second option is far more common and practical. So perhaps insurers took some inspiration from it.
When pigs fly
Another trend is the gradual reduction of exclusions in policies and of agreed limits. Property owners are often astonished to find out what their insurance, which they have been paying for many years, does not cover at all. And it is not just the notorious cases of houses in flood-prone areas whose owners paid expensive premiums for decades completely in vain.
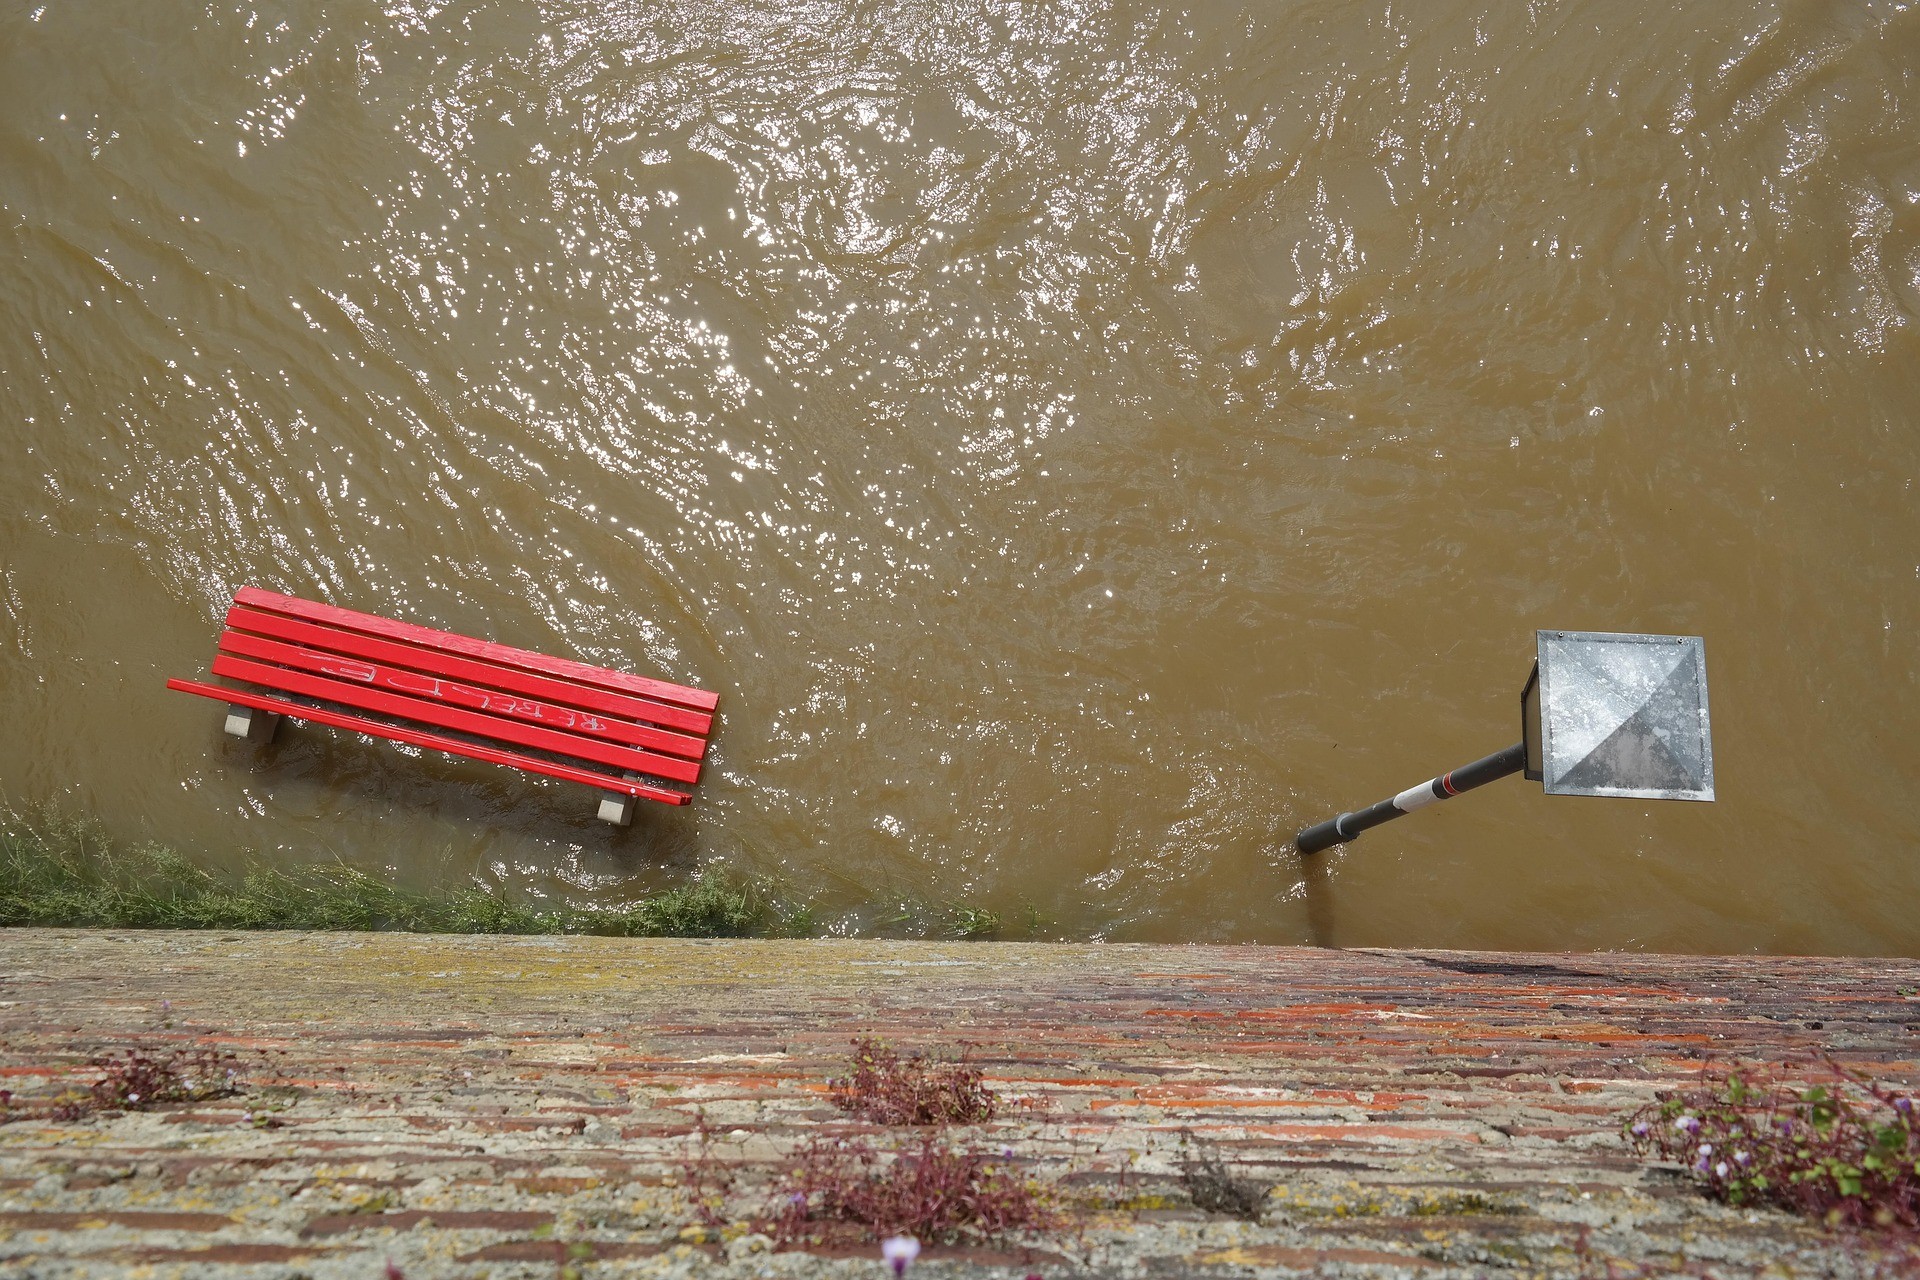
One thing is certain – the water took the house. But do we know for sure whether it was a flood or inundation?
For example, limits on rainfall volumes mean in practice that even if a house is swept away by a flood, the insurer will wash its hands of the case if, say, the daily rainfall total in the area exceeded 100 millimetres (or another agreed figure). Yet that is, by the very nature of things, the main reason why the flooding occurred in the first place. In such situations some insurers can be incredibly creative, and loss adjusters, unlike policyholders, have a perfect grasp of what is covered in the policies and how.
Specifics of insurance policies for rental flats
A particular situation arises with property insurance (and contents insurance) where you offer the property for rent. It is essential to keep very careful track of what is covered by the policy taken out by the owner, and what should instead be arranged by the new tenant. If you would like to know which risks you should not overlook, or want to read why taking out liability insurance is a genuinely new idea, be sure to open the separate article on the FLAT SERVICE blog devoted to this topic. Do you have an investment flat in your portfolio and would you rather leave the administration that inevitably comes with renting to someone else? Then don't hesitate to turn to the experienced property management company FLAT SERVICE, which will take care of everything necessary for you. We will save you time and worry and send the agreed rent to your account every month, whatever happens. Just call +420 277 000 330 or write to sales@flatservice.cz.